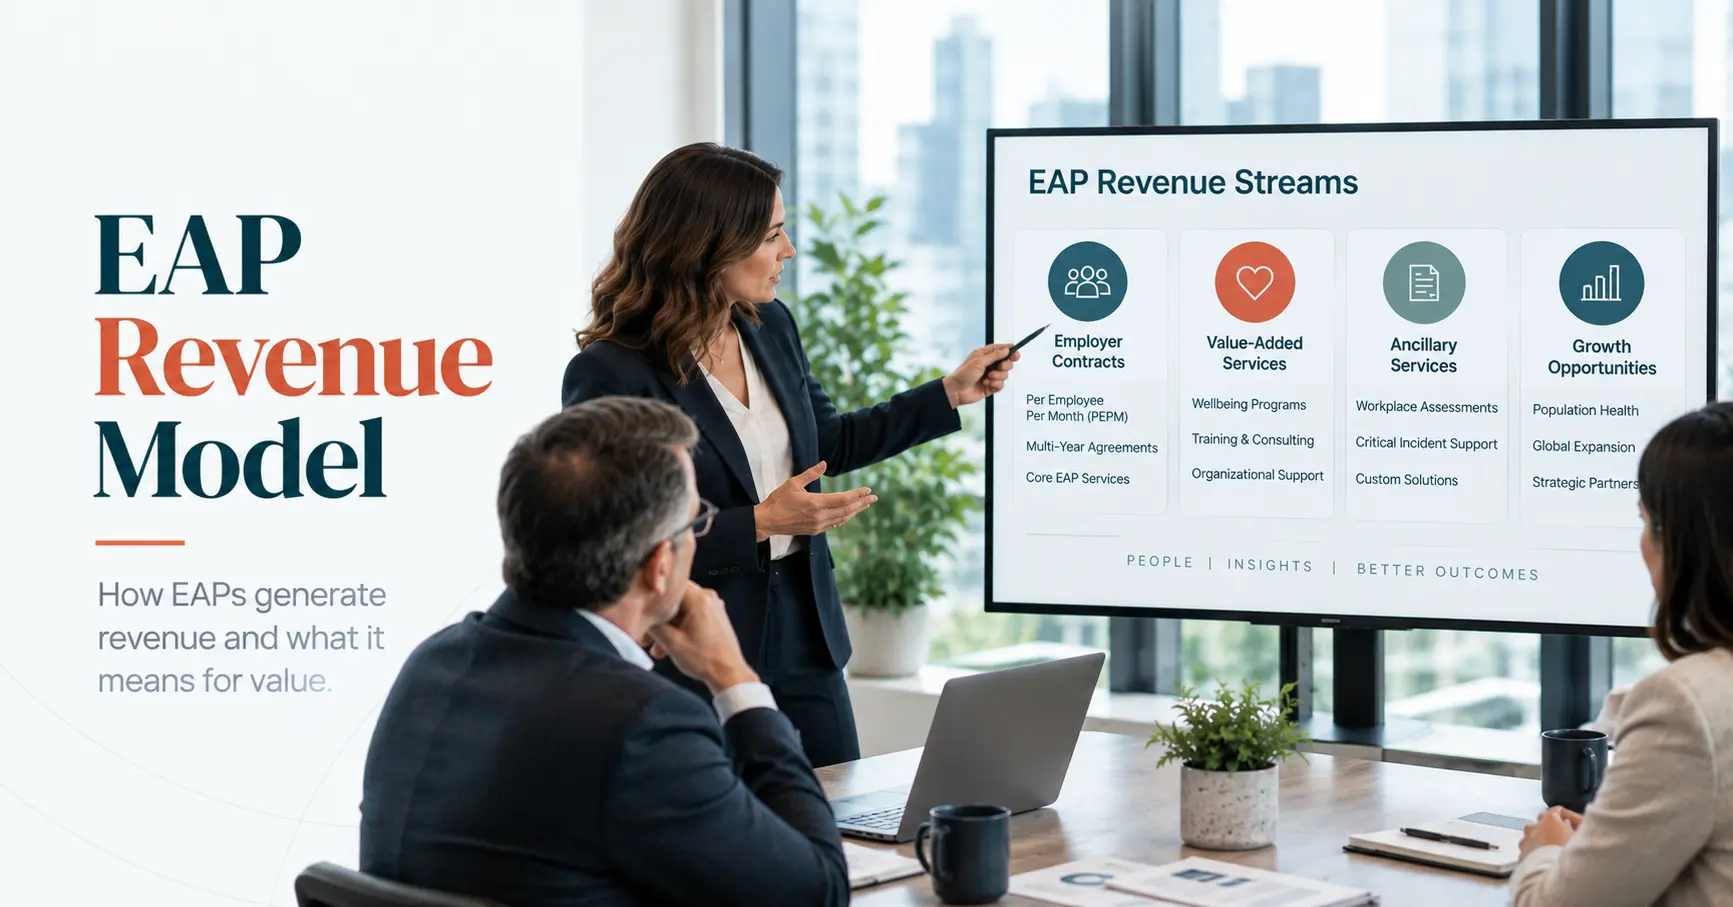
There’s a question buyers ask early in a conversation that catches employee assistance program (EAP) owners off guard. Not “what’s your revenue,” and not “what’s your margin.” It’s: how do you charge?
The reason is that your EAP revenue model determines how everything else on the P&L gets read. Contracted per-employee-per-month income and project-based crisis work can produce identical dollars and get underwritten completely differently, because one of them is a promise about next year and the other is a record of last year.
This is how the three EAP revenue model structures work, what each does to your economics, and why the mix matters more than most owners realize.
Why buyers ask about your EAP revenue model before they ask about profit
A buyer is not buying your history. They’re buying a forecast, and they have to be able to defend that forecast to an investment committee or a board.
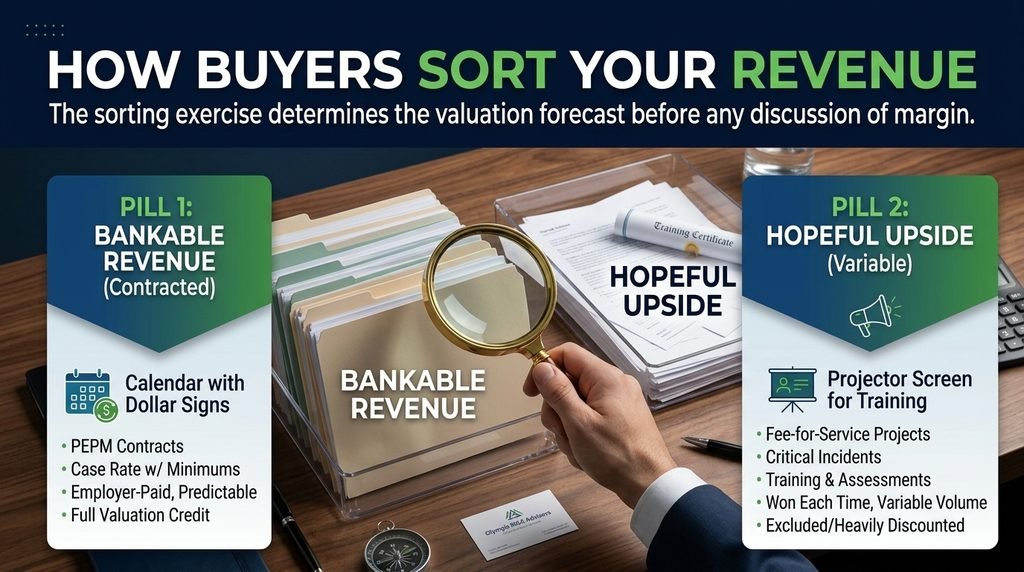
So the first thing they do with your business is sort it into revenue they can bank on and revenue they have to hope for. Contracted, recurring, employer-paid income goes in the first pile. Everything variable goes in the second. Then they build the model largely on the first pile and treat the second as upside they haven’t paid for.
That sorting exercise happens before anyone looks at your margin. Which means your EAP revenue model is doing work on your valuation before the conversation has properly started.
It also explains something owners find genuinely irritating: why a competitor with lower revenue and a duller service offering sometimes gets more attention from acquirers. Usually it’s because their book sorts cleanly into pile one.
The three EAP revenue model structures
Most EAP businesses run an EAP revenue model that blends all three. Very few run only one.
| PEPM / PMPM | Case rate | Fee-for-service | |
|---|---|---|---|
| How you’re paid | Fixed monthly fee per covered employee | A set amount per case opened | Per unit of work delivered |
| Revenue predictability | High — contracted, invoiced regardless of usage | Moderate — varies with case volume | Low — has to be won each time |
| Who carries utilization risk | You | The employer | The employer |
| Margin behavior | Falls as utilization rises | Broadly stable per case | Varies by engagement |
| Typical scope | Core counseling, work-life, referral | Counseling episodes, sometimes tiered | Critical incident response, training, coaching, assessments |
| How a buyer treats it | Underwritten as recurring | Underwritten with a volume assumption | Largely excluded or heavily discounted |
Illustrative framework — not transaction guidance.
The important column is the last one, and it is the one nobody explains to sellers before diligence.
PEPM: the one that attracts capital
A PEPM contract charges the employer a fixed fee per covered employee per month, for an agreed scope of services, regardless of how many people use it. Reported PEPM pricing commonly falls somewhere around USD 1–5 per employee per month depending on scope (GlobalGrowthInsights, February 2026), though the number varies widely with what’s included.
This is the EAP revenue model that made the category investable. It converts counseling into something that behaves like a subscription: contracted, employer-paid, invoiced monthly, renewable annually. That’s why private equity is here at all. Stone Point Capital, for example, has held ComPsych since 2017 (Stone Point Capital, accessed August 2026), and the underlying appeal of the category is exactly this revenue shape.
What PEPM does for you: predictable cash flow, straightforward budgeting for the client, and a revenue line a buyer will underwrite at close to face value.
What PEPM does to you: you own the utilization risk. Entirely. Every case is a cost against a fee that doesn’t move. If usage climbs and price doesn’t, margin erodes quietly and you may not see it for two renewal cycles. That relationship is the whole subject of the EAP utilization rate piece, and it’s the single most common blind spot in this sector.
What buyers look at inside your PEPM book: contract term, escalators, renewal evidence, termination-for-convenience rights, and minimum-fee floors. A PEPM book with three-year terms and annual escalators is a substantially different asset from one with rolling annual contracts terminable on short notice. Same pricing model, different underwriting.
Case rate: the EAP revenue model with better economics and worse underwriting
A case rate charges the employer a set amount each time a case is opened, sometimes with a minimum annual commitment, sometimes with tiers by case type.
The economics are, in one specific sense, more sensible than PEPM. You get paid for what you deliver. Utilization risk sits with the employer rather than with you, so a surge in demand doesn’t quietly eat your margin. Owners running case-rate books often have cleaner unit economics than their PEPM peers and know their delivery costs better, because the model forces them to.
And yet case-rate books frequently get underwritten more conservatively. Here’s why.
The buyer has to assume a volume. With PEPM, next year’s revenue from a contract is essentially known: employee count times rate times twelve. With a case rate, it’s case volume times rate, and case volume is a behavioral forecast. If your case volume has been stable and you can evidence it across three years, that assumption is easy to defend. If it’s been volatile, or if you can’t produce contract-level history, the analyst will use a conservative number and your revenue line shrinks on their model before anyone discusses a multiple.
Minimums change the picture materially. A case-rate contract with a meaningful annual minimum fee behaves a lot like PEPM for underwriting purposes, because there’s a contracted floor. If your case-rate agreements carry minimums, make sure that’s front and center in your materials. It’s commonly buried in a schedule and missed.
The practical takeaway for a case-rate-weighted owner is not “switch to PEPM.” It’s evidence your volume. Three years of case counts by contract, with the drivers you understand, turns a forecast into a track record.
Fee-for-service: the EAP revenue model buyers won’t pay for
Critical incident response. Manager training. Organizational consulting. Executive coaching. Fitness-for-duty and DOT assessments. Wellness workshops.
This work is often the best margin in the business and the most professionally satisfying part of it. It’s also the part a buyer will largely refuse to pay for.
Not because it isn’t real. Because it isn’t contracted. Every engagement has to be won again, and a buyer underwriting a forecast can’t assume a critical incident will happen or that a client will book training next year. So fee-for-service revenue typically gets excluded from the recurring base or discounted heavily, and it lands as upside the buyer hasn’t paid for and will happily keep.
There are two ways to change that, and both take time.
Contract it. Some of this work can be moved into the recurring agreement — a training allocation, an included number of critical incident hours, a retainer for organizational consulting. You may get less per unit. You’ll get credit for all of it.
Evidence it. Where genuinely recurring patterns exist — a manufacturer who books the same four training days every year, a healthcare system with predictable annual incident volume — document the pattern by client across several years. It won’t get treated as contracted revenue, but a consistent multi-year history argues for a much softer discount than a scattered one.
Owners are often reluctant to hear this because fee-for-service work is where their expertise shows. That’s fair. It just isn’t what’s being purchased.
What contract minimums do to your EAP revenue model
Annual minimum fees deserve more attention than they get, because they quietly convert variable revenue into something closer to contracted revenue, and almost nobody presents them properly.
A case-rate agreement with a $48,000 annual minimum is, from an underwriting perspective, $48,000 of contracted income with case-rate upside attached. That’s a fundamentally different asset from an open-ended case-rate agreement with no floor, even if both billed the same amount last year.
The problem is that minimums usually live in a pricing schedule at the back of the contract rather than in the commercial summary anyone reads. So when materials get prepared, the revenue gets presented as “case rate,” the analyst applies a case-rate assumption, and the floor never enters the model.
Two practical moves. First, build a one-page schedule showing every contract, its structure, and its annual minimum where one exists — total the floors. That total is your contracted base, and it’s likely larger than you think. Second, at renewal, ask for minimums on the case-rate agreements that don’t have them. Employers often accept a modest floor in exchange for rate certainty, and each one you add converts a forecast into a contract.
What happens to your EAP revenue model after a sale
Worth knowing before you choose a buyer, because different acquirers do different things to how you charge.
A strategic consolidator usually migrates you onto their paper. At renewal, your contracts move to their standard agreement, their pricing structure and often their PEPM bands. If your rates sit below theirs, that’s upside they’re buying. If they sit above, some of your clients will see a change they didn’t ask for, and the renewal risk that creates is exactly what an earnout tends to sit on top of.
A private equity platform is more likely to leave pricing alone initially and standardize reporting first. Their early work is usually systems, financial visibility and contract-level economics, because that’s what supports the next acquisition. Repricing tends to come later, once the data supports a case.
A digital mental health acquirer may change the product, which changes the pricing. If the EAP becomes a component of a broader stack sold at a different price point with a different scope, your existing per-employee-per-month structure may not survive the transition intact.
None of these is a reason to prefer one buyer over another. It’s a reason to ask the question directly before granting exclusivity — “what happens to our pricing and our contracts at the first renewal after close?” — and to notice whether the answer is specific. Pillar 3 covers what each buyer type is actually buying, which usually predicts the answer.
What the right EAP revenue model mix looks like
There’s no ideal EAP revenue model ratio, and anyone quoting one is guessing. But there is a useful way to think about it.
Your contracted base should be able to carry the business. If PEPM and case-rate minimums cover your fixed costs with something left over, you have a business that survives a slow year for project work. If you need the fee-for-service line to break even, you have a services firm with an EAP attached, and it will be valued more like the former than the latter.
Your variable work should be growing off a documented base, not filling holes in it. There’s a real difference between a business where project revenue is expansion into existing accounts and one where it’s plugging churn in the contracted book. The first reads as land-and-expand. The second reads as a retention problem.
Your EAP revenue model should match your delivery model. If you run a thin affiliate network in a region and win a large PEPM contract with high expected engagement, you’ve taken utilization risk you may not be able to service economically. Case rate would have been the safer structure for that client. These decisions get made under sales pressure and live with the business for years.
If you’re weighing changes to your EAP revenue model ahead of a sale, the sequencing matters — moving contracts between structures happens at renewal, which means the work runs on your clients’ calendar, not yours. Two years is a realistic horizon for changing the shape of a book. Six months is not.
The valuation pillar covers how revenue mix feeds into adjusted EBITDA and the multiple. Pillar 4 explains what happens when a buyer decides part of your revenue is too variable to pay for at closing, which is usually an earnout. And if you want the wider context on why capital finds this sector attractive in the first place, that’s in the consolidation piece.
A closing thought for anyone reading this with a book that is heavier on project work than they would like. That weighting usually exists for a good reason. It is what clients asked for, what your team is best at, and often what kept the lights on during a thin year. Nobody is suggesting you should have built it differently, and a buyer who dismisses that work has misread what makes an EAP business durable in the first place. The point is narrower than that: know how each dollar will be read before someone else reads it, so the conversation about your EAP revenue model happens on your terms rather than in the middle of diligence.
Owners thinking through revenue mix before deciding on timing often test the analysis against live transaction activity first. Specialist sell-side firms including Olympic M&A have that conversation years ahead of a process, and there’s no cost to having it early.
Frequently asked questions
How do EAP companies make money?
EAP companies are paid by employers rather than insurers or individuals, most commonly through a fixed per-employee-per-month fee covering an agreed scope for all covered employees regardless of usage. Additional revenue comes from case-rate arrangements and fee-for-service work such as critical incident response and training.
What is a PEPM contract?
A PEPM contract charges an employer a fixed fee per covered employee per month for a defined scope of services, billed regardless of how many employees use the program. It produces predictable contracted revenue for the provider, who in exchange carries the risk that utilization exceeds pricing assumptions.
What is the difference between case rate and PEPM?
Under PEPM, the provider bills a fixed monthly fee per covered employee and carries utilization risk. Under a case rate, the provider bills a set amount per case opened, so the employer carries utilization risk. PEPM is more predictable for buyers; case rate often has cleaner unit economics.
Which EAP revenue model is worth more in a sale?
Contracted PEPM revenue is generally underwritten closest to face value because it is predictable and employer-paid. Case-rate revenue is underwritten with a volume assumption, more favorably where annual minimums exist. Fee-for-service revenue is commonly excluded or heavily discounted.
Should I move my EAP contracts from case rate to PEPM before selling?
Not automatically. Case-rate books with evidenced multi-year volume history and annual minimums underwrite well. Switching your EAP revenue model also transfers utilization risk to you, which can damage margin if your delivery cost per case is not well understood. Evidence the volume before restructuring the pricing.